Satire and commentary · 28.09.2026
Escape from the Golden Cage
UBS threatens to leave Switzerland. At last, a cellmate richer than I am.
← All articles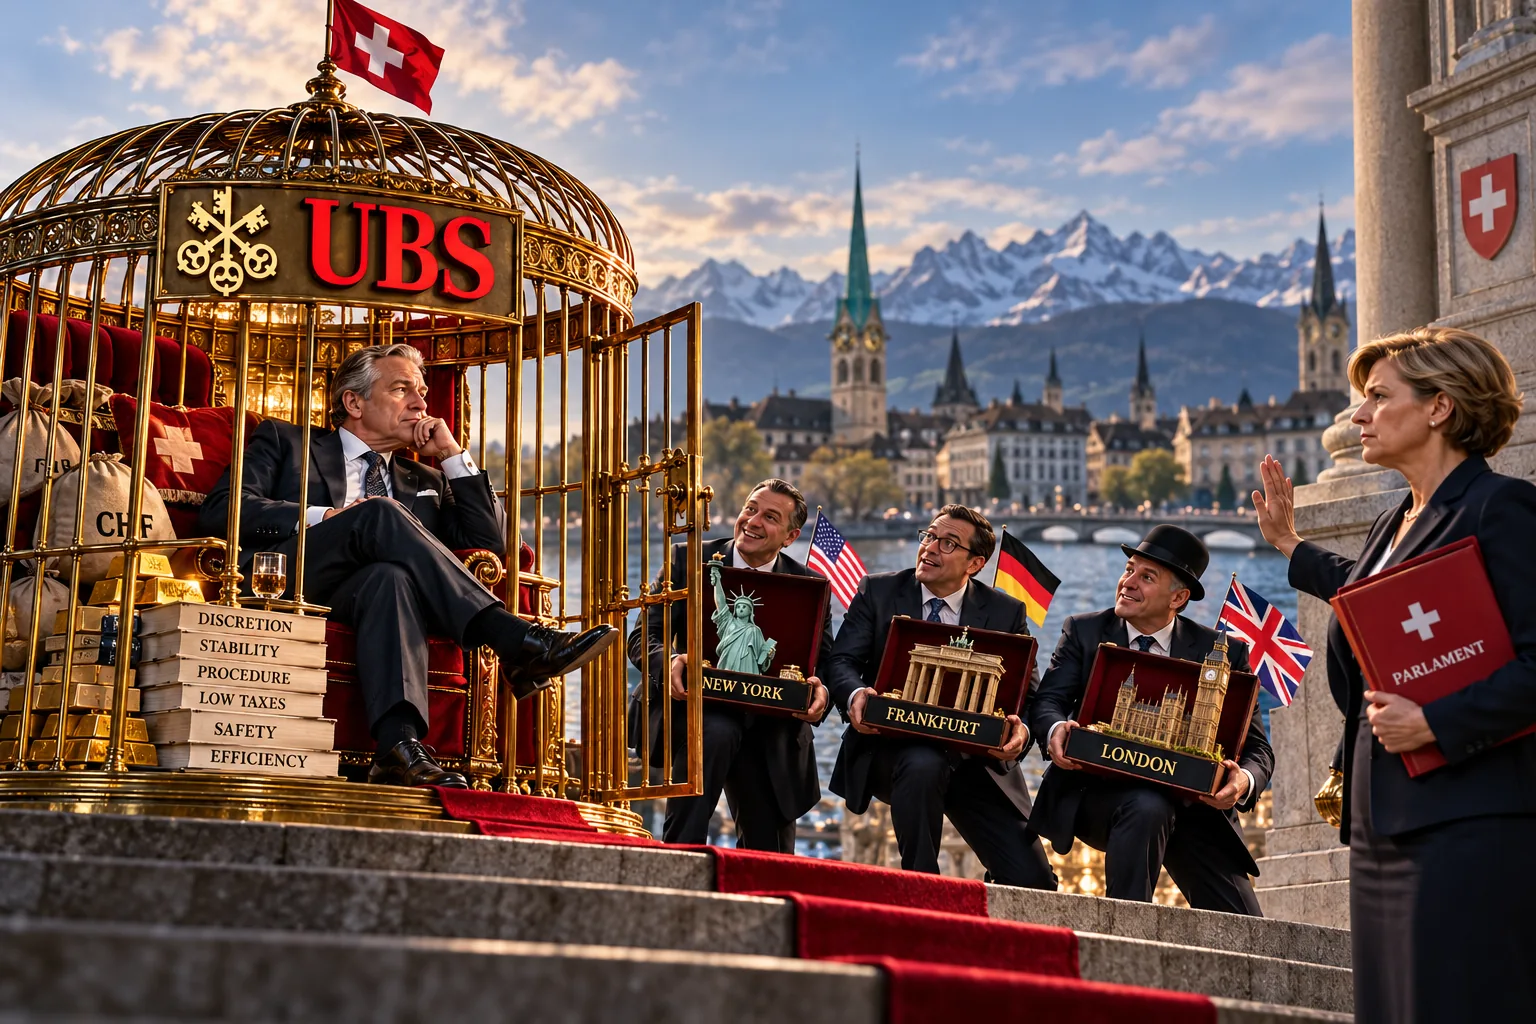
For years I felt alone. A Neapolitan transplanted among the Alps, complaining about the golden cage: compulsory quiet after ten at night, the communal laundry booked with the solemnity of a heart transplant, the note from a neighbour — anonymous, in block capitals, complete with a citation from the building rules — because I had put green glass in the brown-glass container. I thought I was the problem. The southerner who fails to integrate. The one to whom people explain, with infinite patience, that “we don’t do that here”.
Then, this week, I discovered that I have a distinguished cellmate. One hundred and sixty-four years of history, a balance sheet roughly twice the size of Swiss GDP, a logo with three keys, and a name that until the day before yesterday was synonymous with Switzerland, like chocolate, watches and the bank accounts best left unmentioned over dinner. UBS.
UBS wants to leave too. UBS, too, finds the bars too close together.
Welcome to the club, dear. Lunch is served at noon sharp, and complaints must be submitted in triplicate.
What happened
A recap for anyone who does not spend their evenings reading the minutes of the Council of States (lucky you). On 23 September, the upper chamber of parliament decided that UBS’s foreign subsidiaries should be backed by 90% CET1 capital — real capital, the sort you cannot conjure up in a spreadsheet and which, unlike promises, is still there on Monday morning — compared with the current combination of 45% CET1 and 17% in AT1 bonds. By the bank’s calculations, that means about $16 billion more. Add what it already owes after Credit Suisse and the total comes to around $30 billion, with an estimated annual cost of $2.5 billion.
To put it plainly: it is like asking someone who bought the neighbour’s burnt-out house for a song to install at least one fire extinguisher. All hell breaks loose.
The next day, as punctual as a Swiss Federal Railways train on a good day, Semafor reports that people at the top of UBS have resumed discussing ways to escape Swiss supervision. Perhaps through a merger, which in banking is an elegant way of saying “I’m changing my surname”. The luxury candidate: Morgan Stanley, which has long eyed UBS’s roughly $7 trillion in assets under management the way a cat eyes an aquarium. Cheaper alternatives: Standard Chartered or Deutsche Bank. Like a restaurant where the sommelier sees your face and offers you the house wine as well.
On Friday, the shares rise 3.5%. Read that again, slowly: investors celebrated the idea that the quintessential Swiss bank might cease to be Swiss. At a wedding, this would be the moment when the guests applaud the announcement of the divorce, stand up and ask for the lawyer’s number. Not the finest advertisement for Swissness.
A quick refresher (for those with short memories, which means everyone)
March 2023. Credit Suisse sinks. In a single weekend — a national speed record in a country where moving a tram stop takes a consultation, two appeals and a referendum — the state wraps up the rival and gives it, pardon, sells it to UBS for about 3 billion francs. On the side: a public guarantee of 9 billion and a mountain of liquidity from the National Bank. Credit Suisse shareholders get the crumbs, AT1 bondholders are wiped out, and UBS becomes Switzerland’s only global-sized bank. Too big to fail. Too big to be rescued a second time. Above all, too big to be told no.
Three years later, the Confederation appears cap in hand — yes, it is the state asking politely: since, if you fall, we all fall, could you put a little capital aside? And the bank, according to the finance minister, calls every proposal extreme. Extreme. From an institution with a balance sheet twice the size of the economy hosting it.
Here is the golden cage turned inside out. When a rescue is needed, one is Swiss to the marrow, a white cross tattooed on the heart. When it is time to pay the insurance premium, one suddenly discovers oneself a citizen of the world, stateless by vocation, nobody’s child.
Quanno 'a banca chiagne, 'o contribuente paga. When the bank cries, the taxpayer pays.
The most honest sentence of the year
Now comes the moment that alone makes the week, perhaps the whole parliamentary term, worthwhile. Interviewed by the Aargauer Zeitung, Karin Keller-Sutter recalls the concessions already made to the bank and then remarks, in the tone one uses to announce the post office’s closing time, that UBS has gone all in on an aggressive strategy, presumably confident it would win in parliament anyway. After all, “that’s always been the case in the past”.
Let us stop and read that again. It was not said by an activist in sandals outside Paradeplatz. It was not said by a grumbling Neapolitan with a book to sell (ahem). It was said by the Confederation’s finance minister: when the bank was involved, parliament usually sided with it. Usually. Indeed, always. In the countries to which Switzerland likes to give lessons in good governance, this phenomenon has a technical name. Here it is called tradition.
In Italy, a sentence like that would have produced three television debates, two commissions of inquiry, a parliamentary question and a meme of the minister’s face. In Switzerland it was Saturday: the newspaper ended up in Tuesday’s waste-paper collection, folded, tied with string and placed on the pavement at seven sharp, as municipal regulations require. Here, even scandal is recycled.
The brand on the cage
The minister adds a delightful argument: outside Switzerland, UBS would no longer be a Swiss bank, whereas its entire business model rests on Swissness, the rule of law and political stability.
The rule of law, indeed. The one that, in March 2023, made billions in bonds evaporate on a Sunday afternoon under an emergency ordinance. Very stable. Especially if you were sitting on the right side of the table.
And then Swissness. Remember that word; it is the key to everything. Switzerland is not a country: it is a registered trademark, available for rent. Ask Toblerone: when it moved part of its production to Slovakia, it had to remove the Matterhorn from its packaging. I wonder whether UBS will have to remove the three keys from its logo — trust, security, discretion.
Three keys. And all this time they have had the keys to the cage in their own pocket. Now they threaten to take them away, like a tenant moving out without returning the set to the building manager.
Who can leave, and who cannot
The golden cage does have a door. It simply does not open the same way for everyone.
If you are an ordinary person, Switzerland welcomes you with a B permit, perhaps later a C permit, an integration test in which you must prove that you know the paper-collection days by heart, a lease with three months’ notice at fixed dates and building regulations longer than the Federal Constitution. Lose your job and your permit wobbles. Complain and you are ungrateful. Threaten to leave and they help you pack, reminding you to return the flat clean, with the nail holes filled in.
If you are a big bank, you threaten to leave and your shares gain 3.5%. And the minister, instead of reminding you about the nail holes, gives an interview to explain that you would be worse off outside.
For us mere mortals, Switzerland is a cage. For those with enough capital, it is a five-star hotel: have breakfast, put the brand on your letterhead, order a rescue through room service, then threaten to change hotels when the bill arrives. The staff naturally apologise for the inconvenience.
The language of goodbye
Besides, the bank had been preparing us, with the delicacy of a lover making an escape. January 2025, chief executive Sergio Ermotti: leaving Switzerland is not even something to consider at this stage. September 2026, chairman Colm Kelleher at the bankers’ gathering in St Gallen: the goal is to stay, but if we were no longer competitive we would naturally have to think about it. This is the banking version of “it’s not you, it’s me”. With the divorce lawyer already waiting outside.
Last year, in Hong Kong, the same Kelleher diagnosed Switzerland with an identity crisis. From a bank considering becoming American, German or British depending on the offer, that is like taking lessons in fidelity from Casanova. Kelleher, incidentally, came from Morgan Stanley. Perhaps it is a coincidence. In Switzerland, coincidences are the one thing that never arrives on time.
As for fidelity, the bank has a record. In 2009, pressed by the American tax authorities, it paid $780 million and handed Washington the names of hundreds of clients who had chosen Switzerland precisely for its legendary confidentiality. Trust, security, discretion: the third key had the day off.
How it will end
The minister says that leaving would be much more expensive and legally complicated; that she did not call Ermotti after the vote because there was no need; and that she will see Kelleher in November, though not to negotiate: the matter is before parliament. Translated into Swiss: keep calm, follow procedure, take minutes, then have an aperitif.
Of course, across the Atlantic — so people were whispering even last year — a more permissive regulatory environment awaits. More permissive than Switzerland. I had to sit down when I read that.
My bet, all the same, is that UBS will not leave. Nobody ever really leaves the golden cage. You threaten, bargain, shave decimal points, find a compromise that disappoints everybody with clockwork precision. And in the end you stay, because the world outside is not so orderly, so discreet, so understanding towards those with money.
I know. I tried it myself.
You do not escape the system. You become part of it. That goes for a Neapolitan who always keeps a packed suitcase under his bed and, apparently, for a 164-year-old bank too.
Everything works. That is precisely the problem.
I write about golden cages, systems that work rather too well and the people who remain inside them in Switzerland, the Golden Cage by Leonardo Mascia.
Sources and clarifications
The merger and relocation are possibilities reported by Semafor, not decisions announced by UBS. The additional capital figures are the bank’s estimates. AT1 bonds were written down in 2023; in 2025 the Federal Administrative Court annulled FINMA’s decision, which FINMA has appealed.
- Parlamento svizzero · voto del Consiglio degli Stati e livelli CET1/AT1
- UBS · stime sui requisiti patrimoniali
- Semafor · ipotesi di trasferimento e fusione
- SWI swissinfo · intervista a Karin Keller-Sutter
- Dipartimento federale delle finanze · acquisizione Credit Suisse e AT1
- Tribunale amministrativo federale · sentenza parziale sulle AT1
- FINMA · ricorso contro la sentenza sulle AT1
- US Department of Justice · accordo UBS del 2009